WANT THIS ISSUE?
Download your own personal copy of this issue in PDF format. Click the button below:
WANT THIS ISSUE?
Download your own personal copy of this issue in PDF format. Click the button below:
The April-May 2020 issue of Generations Magazine, Hawai‘i’s Resource for Life, features an in-depth look at Leslie Wilcox, President and CEO of PBS Hawaii, we look at lifework and planning amid Covid-19, the expansion of telehealth services and a look at solutions for loneliness and housng.
 Cybercriminals and online fraudsters are sending out phishing emails, text messages and setting up robocalls offering “discounted” coronavirus test kits, masks and even hand sanitizers — all bogus offerings — in an attempt to scam the public.
Claiming to be medical experts, they are also advertising bogus treatments and vaccines.
They are also creating fake websites purporting to be the Centers for Disease Control and Prevention (CDC), the World Health Organization (WHO) or even the Internal Revenue Service (IRS), and tricking unsuspecting visitors into clicking on links that will infect their devices with malware that steals financial and personal information.
Phishing emails have also offered to expedite government relief checks.
Here are some preventive tips on how not to be duped by these cybercriminals:
• Beware of online requests for personal information, such as your Social Security number.
• Check the email address or link. You can inspect a link by hovering your mouse button over the URL to see where it leads.
• Do not click on links in emails or texts.
• Watch for spelling and punctuation mistakes, and bad grammar.
• Beware of contact tracing scams. Do not provide personal information or click on any links from an unverified source.
• Avoid emails that insist you act now. Phishing emails often try to create a sense of urgency or demand immediate action.
• Do not download, view or open any email attachments sent to you.
• Do not reply to the email, text message or robocall.
• Ignore online offers for vaccinations. They do not exist yet.
• Be wary of ads for test kits. Most test kits being advertised have not been approved by the FDA and are not accurate.
If you feel you have been victimized by a scam, contact your financial institution or credit card company, and report it to your local law enforcement agency.
THE DEPARTMENT OF THE PROSECUTING ATTORNEY
1060 Richards St., Honolulu, HI 96813
808-768-7400 | Office hrs: Mon – Fri, 7:45 am – 4:30 pm
www.honoluluprosecutor.org/contact-us/
It may be hard to believe, but even during the coronavirus pandemic, criminals are targeting and preying upon the public via phony websites, bogus emails and text messaging, and by phone.
As I indicated in the last issue, under Hawaii Revised Statute §514E-9, timeshare companies are required to give clients all information regarding the unit for purchase, including all the fees attributed to that unit that are due immediately and the “hidden” fees that require seemingly endless future payments — the monthly mortgage, property tax, maintenance fees and interest.
 Don’t Succumb to Pressure
Because timeshare agents usually don’t verbally deliver the “caveats” of the transaction to the clients, it is with utmost importance that prospective timeshare buyers read through those contracts thoroughly. If the salesman tries to subtly pressure you into just signing the paperwork and indicates you can change your mind later, stand up and walk away.
There have been local stories of people feeling trapped in the sales pitches, having their intelligence questioned, having their emotions played upon and being made to feel guilty for “wasting” the salesman’s time.
How to Exit From Ownership
If you have actually bought into a timeshare and you can no longer afford it, options include renting or selling, going into foreclosure, or hoping that the hotel/resort can take back the deed of the unit if the mortgage agreement will allow it.
These options in exiting a timeshare, however, are fraught with pitfalls. It’s important to verify the legitimacy of the companies that approach for the purpose of resale. There are also signs to be wary of, including huge initial fees, overseas bank account addresses for wire transfers and asking for personal or financial information. Reputable companies will use written contracts specifically outlining the services to be provided. These contracts should include the services the resellers will perform, outlined fees with deadlines, the length or term of the contract to sell the timeshare, and it should note the person responsible or documenting and closing the sale.
A timeshare is not a bad thing in itself. It is the lack of understanding of the industry and contracts that lead people to become victims of the system. So, read and understand the details of everything you sign — or prepare for unforeseen and unpleasant consequences.
If you suspect elder abuse, call these numbers:
– Police: 911
– Adult Protective Services: 808-832-5115
– Elder Abuse Unit: 808-768-7536
If you have questions about elder abuse, call or email:
808-768-7536 | ElderAbuse@honolulu.gov
As I indicated in the last issue, under Hawaii Revised Statute §514E-9, timeshare companies are required to give clients all information regarding the unit for purchase, including all the fees attributed to that unit that are due immediately and the “hidden” fees that require seemingly endless future payments — the monthly mortgage, property tax, maintenance…
As a member of ACTEC, I am privileged to learn from and exchange ideas with some of the most skilled and dedicated trust and estate lawyers in Hawai‘i. I often wonder why most of our discussions focus on probate and litigation issues rather than on how we can help plan to mitigate family conflict and avoid probate.
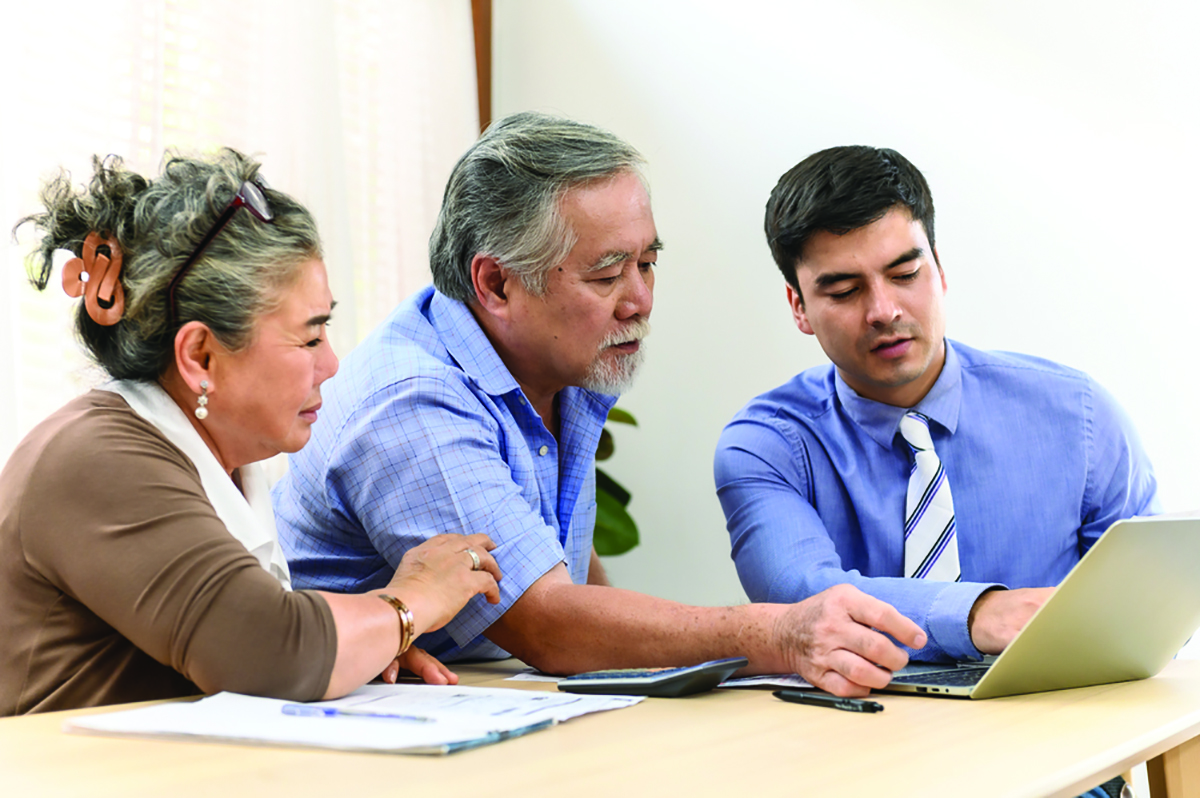 As professionals, we must continue to fight against the inclination to treat estate planning as “the preparation of documents.” Rather, we ought to consider ourselves more as counselors of law” who guide their clients through a process that considers all factors — understanding clients’ intentions and hopes, first and foremost — as well as convenience, probate avoidance, minimization of tax, family relationships, liability and fashioning a plan well-suited to their unique needs. This includes proper counseling and assistance in the funding of a trust, and engaging in meetings with family members and professionals to communicate intentions and the plan so that everyone — family, client and professional — are working together seamlessly with common goals.
Estate planning is not a commodity of different pieces of documents put into a three-ring binder. Estate planning mirrors life, where change is constant and communication is key.
STEPHEN B. YIM, ATTORNEY AT LAW
2054 S. Beretania St., Honolulu, HI 96826
808-524-0251 | www.stephenyimestateplanning.com
As a member of ACTEC, I am privileged to learn from and exchange ideas with some of the most skilled and dedicated trust and estate lawyers in Hawai‘i. I often wonder why most of our discussions focus on probate and litigation issues rather than on how we can help plan to mitigate family conflict and…
When I was in elementary school in the 1960s, my family’s set of encyclopedias claimed that I could expect to live to the ripe old age of 70. That seemed incredibly old to me. Fast-forward to 2020, and the current consensus is that I will live into my 80s, barring a catastrophic illness or an accident. Advances in medical science are probably the primary reason for this difference, but now, when 80 seems pretty young to me, I have to ask, is a longer life necessarily a good thing? It is not that difficult to think of compelling reasons in order to answer that question in the negative.
 Although science has stretched our lifespans, it has not yet perfected a way to keep us mentally and physically competent until the ends of our lives. The net result is that we live longer, but our quality of life in the extra years that science has granted us may not be what we would desire. In our grandparents’ day, senility was not unknown, but back then, most people died before they had a chance to plumb the depths of Alzheimer’s. Each person reading these words must recognize that he or she has about a 70 percent chance of being incapacitated to the point of needing long-term care for some period of time before the final bell.
Planning for the likelihood of eventual incapacity can make our final years much more bearable for ourselves and our loved ones than will otherwise be the case. So each of us needs to include in our estate planning arsenals against the inevitable — not only clear instructions about passing on our things, but also clear chains of authority and clear instructions about how decisions will be made on our behalf if we lose the ability to make those decisions.
Most of us would prefer not to think about these things and most of our children (the good ones, anyway) want to think about them even less. But that is a poor excuse for leaving our loved ones in a haze of difficult decisions that could have been considered, analyzed and planned for in advance. Seeing how our minds and bodies are unlikely to improve over time, a plan delayed may very well end up being a wishful thought and the source of deep regret.
Gather your loved ones and your trusted advisors and document the path that you will follow if time and health take you where you do not want to go. This process requires honesty, courage and wise counsel. Ultimately, it will be a source of tremendous peace.
SCOTT MAKUAKANE, Counselor at Law
Focusing exclusively on estate planning and trust law.
www.est8planning.com
808-587-8227 | maku@est8planning.com
When I was in elementary school in the 1960s, my family’s set of encyclopedias claimed that I could expect to live to the ripe old age of 70. That seemed incredibly old to me. Fast-forward to 2020, and the current consensus is that I will live into my 80s, barring a catastrophic illness or an…
In these challenging economic times, many worthwhile charitable organizations find themselves in a precarious financial position. Meanwhile, they are experiencing unprecedented demand, especially those charities that provide basic needs like food and shelter.
Thankfully, new, unique provisions in the tax code have been implemented in response to the COVID-19 crisis, creating more incentives for giving. You may be able to better leverage your donations with tax-smart strategies. So, if you’re able to extend your generosity during this time of increased need, it may be an opportune year to make charitable contributions.
 Everyone Can Claim a Deduction
In 2020, the standard deduction is $12,400 for a single tax filer or $24,800 for a married couple filing a joint return (even more for those age 65 or over). Your itemized deductions would need to exceed those levels to benefit from itemizing. Those who don’t typically itemize are not able to deduct charitable contributions from their taxes. However, on your 2020 tax return, you will be allowed to deduct up to $300 in cash contributions to qualified charities even if you choose the standard deduction.
A Higher Ceiling on Tax-Advantaged Giving
If you itemize deductions and plan on large gifts, the tax rules prevented you from claiming a deduction that exceeded 60 percent of your adjusted gross income (AGI) in a single year. In a unique provision for 2020, you can now claim a deduction valued at up to 100 percent of your AGI for charitable contributions. If your financial circumstances put you in a position to make substantial gifts, this will be the most favorable year, from a tax perspective, to do it.
A Tax-Efficient Distribution Strategy From Your IRA
A special provision for 2020 allows individuals subject to Required Minimum Distributions from IRAs and workplace retirement plans to forego those distributions. If you don’t need to draw from your IRA to meet your income needs for this year, you still have an opportunity to put the funds that would have been RMD dollars to use as a charitable contribution. The most tax-efficient way to do so is with a Qualified Charitable Distribution (QCD). Up to $100,000 per year can be contributed to charitable organizations in this way. With a QCD, if you are 70.5 or older, funds are distributed directly to the charity from your IRA so you don’t have to claim the income before making the contribution. That is a tax-saving strategy you can use whether you itemize deductions or claim the standard deduction.
Put a Giving Strategy in Place
Your circumstances today and your financial future may require careful reassessment given the current economic challenges. Incorporate your charitable giving strategy into your comprehensive financial plan review. Check with your financial advisor and tax professional as you consider your options for giving in 2020 and beyond.
MICHAEL W. K. YEE, CFP,® CFS,® CLTC, CRPC®
1585 Kapiolani Blvd., Ste. 1100, Honolulu, HI 96814
808-952-1222, ext. 1240 | michael.w.yee@ampf.com
Michael W. K. Yee, CFP,® CFS,® CLTC, CRPC,® is a Private Wealth Advisor, Certified Financial Planner™ practitioner with Ameriprise Financial Services Inc. in Honolulu, Hawai‘i. He specializes in fee-based financial planning and asset management strategies, and has been in practice for 36 years. Investment advisory products and services are made available through Ameriprise Financial Services LLC., a registered investment adviser. Ameriprise Financial Inc. and its affiliates do not offer tax or legal advice. Consumers should consult with their tax advisor or attorney regarding their specific situation. Ameriprise Financial Services LLC. Member FINRA and SIPC. ©2020 Ameriprise Financial Inc. All rights reserved.
In these challenging economic times, many worthwhile charitable organizations find themselves in a precarious financial position. Meanwhile, they are experiencing unprecedented demand, especially those charities that provide basic needs like food and shelter. Thankfully, new, unique provisions in the tax code have been implemented in response to the COVID-19 crisis, creating more incentives for giving.
 By virtue of buying a condominium, each unit owner becomes a member of an association and agrees to share the costs of operating that association. For example, owners share the cost of community lighting, water and grounds-keeping, usually via a set monthly maintenance fee. Special assessments are extra charges unit owners pay to cover larger or unforeseen expenses. They are becoming more common because many condominium associations in Hawai‘i are comprised of aging buildings and infrastructure. Corroded iron pipes and old elevators are a common cause of special assessments.
Association boards have a fiduciary duty to collect funds from owners in order to pay the bills to maintain and make timely repairs to the property and its structures. Boards and associations may incur liability for failing to do so. In addition, the value of the condominium may decrease, and it may become uninsurable.
Sometimes owners are not able to pay these shared expenses and dispute the charges. Failure to remit in a timely fashion can result in penalties, fines, late fees, lien filing fees, attorneys’ fees and costs, liens, and possibly, foreclosure.
 The Hawai‘i State legislature decided that it was important to have clear and effective rules relating to condominium foreclosures and wanted to encourage the use of mediation for penalties and other charges, so it changed both foreclosure and condominium law.
Condo Foreclosure
Under the nonjudicial foreclosure law (chapter 667, Hawai‘i Revised Statutes (HRS)), if the parties have agreed on a payment plan to stop a foreclosure from continuing, unpaid fines assessed by the association are not a default under the plan. (See section 667-94(c), HRS.) As long as the owner is not in default in any other manner under the plan, the association must notify the unit owner in writing of the right to mediation and cannot deduct any fines or attorney fees from the owner’s plan payments. The parties then can attempt to resolve any dispute over fines and attorneys’ fees through mediation within 30 days of the association’s written notice. If, however, the owner refuses to mediate or the parties cannot reach an agreement or the owner defaults under the plan, then the association can start foreclosure proceedings. Different rules allowing for payment plans in judicial foreclosures are set forth under section 667-19, HRS.
Foreclosure Mediation
Under the condominium law (chapter 514B, HRS), any notice of default and intention to foreclose nonjudicially (under section 667-92(a), HRS) must be specifically worded and additionally state that the owner may request mediation by delivering a written request for mediation to the association by certified mail, return receipt requested or hand delivery within 30 days after service of the notice. (See section 514B-146.5, HRS.) If the association does not receive a timely request, it may go ahead with nonjudicial or power of sale foreclosure. If the association receives a timely request, it must agree to mediate and cannot proceed with nonjudicial or power of sale foreclosure until it has participated in mediation or the time for completion has elapsed. The completion of the mediation is time-sensitive (usually 60 days). If the association is using the power of sale provision provided in the condominium law, the power cannot be used in certain situations, for example deployed military outside of the State of Hawai‘i or certain liens based solely on fines, penalties, or legal or late fees. (See section 514B-146.5, HRS.)
Owners should always promptly check with their attorney regarding foreclosure matters and issues.
 Condominium Law
Outside of foreclosure law, under the condominium law, there is also a “pay first, dispute later” provision to protect the integrity of the condominium and in fairness to other owners that everyone pays their share. This provision, however, applies only to common expense assessments which are expenses assessed to all owners in proportion to their interests. It does not apply to other expenses of the association. (See section 514B-146(f), HRS.)
Any payment by an owner must first be applied to outstanding common expenses. Then the payment can be applied to other association charges in a list of priorities (assessed charges such as utility sub-metering and cable then unpaid late and legal fees, fines and interest — by board policy.) If, however, an owner designates that any payment is meant for a specific charge that is not a common expense, the payment may be applied as directed by the owner — even if the common expense remains unpaid. (See section 514B-105(c), HRS.)
Condominium law allows an owner who disputes the amount of assessment to request a written statement about the assessment from the association. (See section 514B-146, HRS.) If the owner disputes the information in the association’s written statement, the owner may request another written statement which states that the owner has no right to withhold common expense assessments, the owner has a right to demand mediation or arbitration regarding the validity of the common expense assessment (provided it is paid in full and current), payment of the common expense assessment shall not prevent the owner from contesting common expense assessment, and if the owner contests any penalty, fine, late or lien filing fee, or other non-common expense assessment, the owner may demand mediation prior to paying those charges. The owner has 30 days from the date of the written statement to file a demand for mediation on the other charges. If the owner does not do so, the association may proceed with collection of the charges. If the owner requests mediation within 30 days, the association cannot collect any of the disputed other charges until it has participated in mediation which must be completed within 60 days of the owner’s request. Only if the mediation is not completed within 60 days or the parties cannot resolve the dispute by mediation may the association proceed with collection of any amounts due for attorneys’ fees and costs, penalties or fines, late or lien filing fees, or any other charge that are not a common expense of all unit owners.
STATE DEPT. OF COMMERCE & CONSUMER AFFAIRS — REAL ESTATE BRANCH
808-586-2644 | www.hawaii.gov/hirec
This information is for educational and informational purposes only. Owners and associations should consult their attorneys for legal advice and assistance.
By virtue of buying a condominium, each unit owner becomes a member of an association and agrees to share the costs of operating that association. For example, owners share the cost of community lighting, water and grounds-keeping, usually via a set monthly maintenance fee.
Social Security and its Office of the Inspector General continue to receive reports about fraudulent phone calls from people claiming to be Social Security employees. These scammers try to trick people into providing personal information or money, and often threaten their victims with arrest. Don’t be fooled.
 Our employees will never threaten you for information or promise a benefit in exchange for personal information or money. Real Social Security employees also WILL NOT:
• Tell you that your Social Security number has been suspended
• Contact you to demand an immediate payment
• Ask you for credit/debit card numbers
• Require a specific means of debt repayment, like a prepaid debit card, a retail gift card or cash
• Demand that you pay a Social Security debt without the ability to appeal the amount you owe
• Promise a Social Security benefit approval or increase in exchange for information or money
If you receive a suspicious call or are unsure of the identity of someone who claims to be from Social Security:
Hang up. Do not give money or personal information.
Report the scam to our Office of the Inspector General at oig.ssa.gov/report.
Call your local SSA office at 800-772-1213 (toll free) Mon–Fri, 8:30am–3:30pm. Use the SSA Office Locator to find your local office at www.socialsecurity.gov
Social Security and its Office of the Inspector General continue to receive reports about fraudulent phone calls from people claiming to be Social Security employees. These scammers try to trick people into providing personal information or money, and often threaten their victims with arrest. Don’t be fooled.
Although new rules and social distancing regulations have been put in place due to the COVID-19 pandemic, there are still resources available to you just a phone call away. Social Security services can be provided at no cost from the safety of your home.
If you are turning 65 or being furloughed from your employer’s group medical plan, you should consider transitioning into a Medicare plan as soon as you are notified. Three months prior to turning 65, you can apply for Medicare Part A , which covers inpatient hospital care with no monthly premium. Your Medicare Part B outpatient coverage will have a monthly premium based on your adjusted gross tax return two years prior to the year you are applying.
 You can obtain the Part B enrollment form CMS 40B online.
If you’re being furloughed, provide your human resources manager with the Request for Employment form CMS L564 (find both forms at www.ssa.gov/benefits/medicare). This form will verify that you’ve had continuous company group medical coverage from your employer. Once Social Security receives both completed forms, they will process your Part B effective date.
COPELAND INSURANCE GROUP
1360 S. Beretania St. Ste. 209, Honolulu, HI 96814
Margaret Wong, Sales & Marketing Director
808-591-4877 | Margaret@Copelandgroupusa.com
www.copelandgroupusa.com
Although new rules and social distancing regulations have been put in place due to the COVID-19 pandemic, there are still resources available to you just a phone call away. Social Security services can be provided at no cost from the safety of your home.
There are many Medicare options available to seniors that will ensure that your medical costs and healthcare needs will be covered in your retirement. But Medicare is complex and difficult to navigate on your own, so it is important that you select a local advisor who knows the Hawai‘i market and will find the right insurance plan for you.
When you are ready to retire, your advisor will meet with you to determine your needs. He or she will check with your physicians, review your prescriptions and find a plan that fits your budget.
 Hawai‘i plans generally range from $0 to $200 monthly, depending on the coverage that is best suited to your needs. Once the ideal plan is selected, the agent will work with you to get you enrolled with the insurance company. After your enrollment, your local agent will be available for followup questions and to address any issues that may arise.
Using a local advisor is the best decision you will make. They know the uniqueness of our Hawai‘i healthcare system and will be by your side to ensure your well-being as you journey through the world of Medicare.
Having a trusted Medicare advisor will help give you the peace of mind that you need in order to pick the perfect plan that will optimize your financial health during your retirement years.
PLAN ADVISORS HAWAII
723 Umi St. Ste. C2, Honolulu, HI 96819
Kalei Kaanoi, Owner
808-200-1676 | kalei@planadvisorshawaii.com
www.planadvisorshawaii.com
There are many Medicare options available to seniors that will ensure that your medical costs and healthcare needs will be covered in your retirement. But Medicare is complex and difficult to navigate on your own, so it is important that you select a local advisor who knows the Hawai‘i market and will find the right…
Preparing yourself with the proper tools helps to make any job a bit easier. If you are baking, you need the proper ingredients. When building something, you need hammers, nails and other related items. It’s the same when you are preparing for your Health Plan Open Enrollment session; or if you are a caregiver, for your person’s Medicare Annual Enrollment. The proper tools include questions you will need to ask yourself and those relating to available options.
Be sure you compare benefits before just looking at the premium amount.
■ Are you considering the best plan for you and your family?
■ What are the annual, maximum, out-of-pocket costs for the plan?
■ Is the plan mostly co-pays (set amounts) or co-insurances (percentage of the cost)?
■ Does the plan have a proactive prevention model that includes wellness classes, a fitness program, basic dental coverage and various ways to access the provider (your doctor or healthcare team), such as in-person and phone appointments, e-visits and video visits?
■ Are the provider locations convenient for you (doctor’s offices or medical facilities)?
■ Are there multiple services offered under one roof to help you spend less time in traffic and more time with family and friends?
■ Are you responsible for helping others find an option that fits their needs?
■ Do they have Medicare? The annual enrollment begins in October, so start looking at options.
 Important question you’ll want to ask about health plans:
■ Do all of your providers accept Medicare and new patients throughout the year?
■ Does this plan have social workers or coordinators who can help you, the caregiver, meet the needs of the person you are caring for?
■ Is there a copay or coinsurance for this service?
■ Is there someone locally who you can meet with virtually or on the phone (for your convenience as a caregiver) regarding your questions?
■ Can they mail or email you the materials before you talk so that you have time to study the benefits and write down all your questions?
The complexities of Medicare and a group health plan can be daunting. Preparing the right questions can be one of your most effective tools.
KAISER FOUNDATION HEALTH PLAN INC.— HAWAII
Medicare Sales: 808-432-5915 | www.kp.org
For more information on resources available to everyone, visit healthy.kaiserpermanente.org.
This information was provided by the Hawaii Kaiser Permanente Medicare Team as an educational resource.
Preparing yourself with the proper tools helps to make any job a bit easier. If you are baking, you need the proper ingredients. When building something, you need hammers, nails and other related items. It’s the same when you are preparing for your Health Plan Open Enrollment session; or if you are a caregiver, for…
Deciding when is the right time to find senior care for your kupuna can be an intimidating task. You want to provide the best care possible for them, but how do you know if it’s the right time; where do you start? First, understand and identify the level of care your senior needs to conduct day-to-day activities and care for themselves. Identifying your senior’s needs early in your search will help you understand the options available. Keep in mind that the level of care can change over time as conditions change.
 There are two main categories for long-term care solutions for seniors: senior communities and residential care homes. In senior communities, kūpuna live together in an apartment-like setting and interact with one another through daily, scheduled activities. They dine with other residents. In residential care homes, three to five seniors are cared for in a home-like setting. Residents get more individualized attention and all of their needs are taken care of.
Finding great healthcare for your loved ones is hard to do on your own. Each year, we see hundreds of seniors in Hawai‘i finding themselves incapable of living independently at home.
How do we get Mom and/or Dad out of the home when they don’t see the need, even though they have fallen multiple times?
After a fall, your senior is feeling fearful and may be resistant to change. During gentle conversations over time, explain that finding care comes from a place of love and wanting them to live a safe and healthy life.
What about dementia care?
Questions to ask a care home or facility about a patient’s dementia care include:
• Is the staff experienced in working with residents with dementia/Alzheimer’s?
• What approaches are used to diffuse a situation with an agitated dementia/Alzheimer’s resident?
• What kind of activities are available to help stimulate a resident’s mind and body?
• Are they open to working with the resident’s geriatric team and family?
CAREGIVER’S HEART
91-1121 Keanui Drive, Ste. 108, PMB 193, Ewa Beach
808-425-5101 | kuunani@caregivershearthawaii.com
www.caregivershearthawaii.com
Deciding when is the right time to find senior care for your kupuna can be an intimidating task. You want to provide the best care possible for them, but how do you know if it’s the right time; where do you start? First, understand and identify the level of care your senior needs to conduct…