Category: Wisdoms

  • The Professional Criminal Magician

    Financial abuse of seniors oftentimes goes unreported. Studies have estimated that as few as 1 in 30 cases are brought to the attention of authorities. There are many reasons why these matters don’t get reported.

    The two main reasons for none reporting are:

    the abuser is a family member and the victim doesn’t want to get them in trouble
    the victim is too embarrassed about being taken advantaged of that they would rather no one know about it than to be humiliated
    The first reason, although misguided, is understandable, but second reason, however, is not.

    To be direct and word this in no uncertain terms, victims of financial abuse should not feel embarrassed about being tricked out of their money. Today’s criminals who target seniors are smart criminals with hundreds of hours of experience and sophisticated tools that can convince even professionals that they are legitimate in their business dealings.
    Generations Magazine- The Professional Criminal Magician - Image 01Encountering today’s scam artist is very similar to seeing a professional magician perform. He has spent countless hours practicing his act, invested in resources and props, and achieved a certain level of competence that earned him his own show. When the audience leaves the performance, they are often left wondering how the tricks were accomplished. They are not, however, embarrassed that they could not figure out how a particular illusion was accomplished. The same should be said about victims of today’s scams.

    An example of the skill level of these criminals is seen in a rash of sweepstakes/lottery scams occurring in the Islands today. Potential victims are sent a personalized message (mail, email or telephone) telling them of their good fortune at winning a prize. How did the criminal get this contact information? They spent money getting it. Just like the magician going into a magic shop to buy a deck of marked cards or a collapsible wand, the scam artist can purchase personal information from various sources including people who steal mail; telemarketers who compile information from people who fill out contest entry forms; or computer programs designed to hack email accounts or link addresses to names.

    Gone are the misspelled, poorly written emails and letters. These scam artists have learned from past mistakes and perfected their trade. Today’s personalized lottery winning letters are well-written and look legitimate. Some include pre-printed checks that will initially fool even a bank teller into giving a sum of money that is suppose to be sent to the scam artist to pay for “taxes and fees” on the prize money. Other letters include a credit card that the victim is told has the lottery winnings on it and it just needs to be activated with a payment.

    So professionally done are these notifications, that some banking personnel, financial planners, lawyers and judges have been fooled by these scams.

    In short, if you have been scammed, do not feel embarrassed. You were taken by a professional. Report the crime so that there is a chance these criminal magicians will disappear. All reports are confidential.


    To report suspected elder abuse, contact the Elder Abuse Unit at: 808-768-7536.
    ElderAbuse@honolulu.gov
    www.ElderJusticeHonolulu.com.
    Financial abuse of seniors oftentimes goes unreported. Studies have estimated that as few as 1 in 30 cases are brought to the attention of authorities. There are many reasons why these matters don’t get reported. The two main reasons for none reporting are: the abuser is a family member and the victim doesn’t want to…

  • Backwards Planning

    In my 19 years as an estate planning attorney, I’ve noticed that many of the things we do as attorneys seem backward. The consequence of backward estate planning is dire, causing failed estate plans and fractured family relationships. To ensure a successful estate plan, we must reverse the way we view many of the common estate planning practices:

    • “Read the Will” prior to, not after, someone dies. In a family meeting, discuss your estate plan. What better time to reveal and clarify intentions than when we are alive.
    • It is not solely the document that makes up a sound estate plan, it is the underlying intent that provides the foundation for each document.
    • Start with “why”, then get to the “how” and “what.” Often lawyers want to rush into telling people what to do without exploring the client’s desires and hopes. If we don’t start with asking why the client wants to complete a plan, the what and how will miss the mark.
    • Stop the tail from chasing the dog. Meaning, lawyers often prioritize artificial tax planning over spending time in the relational aspects of estate planning, only to see that while we may minimize taxes, relationships fail.
    • Mend relationships now. We often avoid strained relationships, and leave it to the estate plan to speak to fractured relationships. While some relationships are not “fixable,” now is the time to try.
    • What is most important is not only equal distribution of assets to our children, but also preserving and nurturing the relationships between those we leave behind.
    • We might feel that it is only the worth (dollars and cents) of our assets that is important. However when pressed, most of us feel it is the value (emotion/relational) of our gift that is our most important legacy.
    • Change “I just completed my plan, now I’m done” to: “I just completed my plan and now I’m ready to start.” Once you’ve signed your estate planning documents, I believe you’ve just started the estate planning process because life changes. Now you’ve committed to something that you can review as change occurs.
    • It’s not an entitlement to receive an inheritance. It’s a loving gift.
    • “It’s family so we don’t have to write legal instructions.” It is because it is family, there is much at stake. The clearer the communicate, the better chance for a successful estate plan.

    Stephen B. Yim, Attorney at Law | 2054 S. Beretania St., Hon. | (808) 524-0251 | stephenyimestateplanning.com

    In my 19 years as an estate planning attorney, I’ve noticed that many of the things we do as attorneys seem backward. The consequence of backward estate planning is dire, causing failed estate plans and fractured family relationships. To ensure a successful estate plan, we must reverse the way we view many of the common…

  • Financial: Time for a Retirement Dress Rehearsal

    Two emotions are likely to strike those who are nearing retirement — excitement and fear. Leaving the world of alarm clocks and cubicles is liberating, but feelings of apprehension about entering a new life stage can easily creep in. The responsibility of pursuing your passions and filling each week in a satisfying way can be a challenge. Then, top that off with the ever-present concern about long-term financial security in retirement.

    Feeling excitement and fear is ok, but what if life after work isn’t everything you envisioned it to be?

    Try A Practice Run

    If you’re nearing retirement, you’ve likely taken steps to prepare financially for the future. But there’s one important thing you might not have considered adding to your pre-retirement checklist — a practice run. How you choose to spend your time (and in many cases, your money) is not always an easy decision. As we age, our interests, hobbies and relationships change. What you may consider your “ideal” retirement when you’re 55 may not fit when you’re 65. This evolution can make it hard to plan accurately for retirement.

    To the extent you’ve made a financial commitment to a certain lifestyle, changing your mind in 10 or 15 years could throw a wrench in your long-term financial plan.

    For example, consider an individual who has lived his entire life in New York, but retires to Florida where taxes and cost-of-living are generally lower. Deciding after several years to relocate back to New York to be near family — where cost of living and tax rates differ — can mean the dollars he’s saved will have to be re-allocated and his savings may not go as far as he’d planned.

    The idea of practicing retirement may also mean leaving the 40-hour work week for something that’s more part-time. Some people may want to take a part-time role with their current employer, or work as a consultant. This also can offer important financial benefits that help preserve their nest egg.

    Financial Rehearsal

    Practice can also be beneficial in another way — simulating how to manage your expenses in retirement. The idea that your cash flow no longer comes from a reliable paycheck, but from other sources like Social Security and personal savings can come as a shock … even to those who are well-prepared for this change.

    One idea to accomplish this is to run two accounts for a certain period of time. Through one account, manage all of your household and lifestyle expenses that you expect during retirement. This includes the costs for necessities such as food, clothing, shelter, utilities, taxes and insurance as well as “nice-to-have” items like dining out, traveling, etc.

    Through the second account, manage all of your expenses that are expected to end in retirement like principal and interest on a mortgage payment (if your home will be paid off), car payments (although car payments can certainly happen again in retirement), college costs for your kids and contributions to retirement plans.

    Perfecting Life In Retirement

    A little practice can go a long way toward easing emotional and financial concerns when it comes to making the jump into retirement. A retirement trial run may not answer all of your questions — and it doesn’t necessarily include the unexpected events that can often throw retirement off track — but doing it for six months or so can be very beneficial in determining whether your retirement budget is realistic. Consider working with a financial advisor who can help you reach your retirement dreams.


    Michael W. K. Yee, CFP
    1585 Kapiolani Blvd., Suite 1100, Honolulu
    808-952-1222 ext. 1240 | michael.w.yee@ampf.com

    Michael W K Yee, CFP®, CFS®, CRPC®, is a Financial Advisor CERTIFIED FINANCIAL PLANNER practitioner™ with Ameriprise Financial Services, Inc. in Honolulu, HI. He specializes in fee-based financial planning and asset management strategies and has been in practice for 26 years. Brokerage, investment and financial advisory services are made available through Ameriprise Financial Services, Inc. Member FINRA and SIPC. © 2014 Ameriprise Financial, Inc. All rights reserved. File # 783860

    Two emotions are likely to strike those who are nearing retirement — excitement and fear. Leaving the world of alarm clocks and cubicles is liberating, but feelings of apprehension about entering a new life stage can easily creep in. The responsibility of pursuing your passions and filling each week in a satisfying way can be…

  • Hazardous Internet Documents

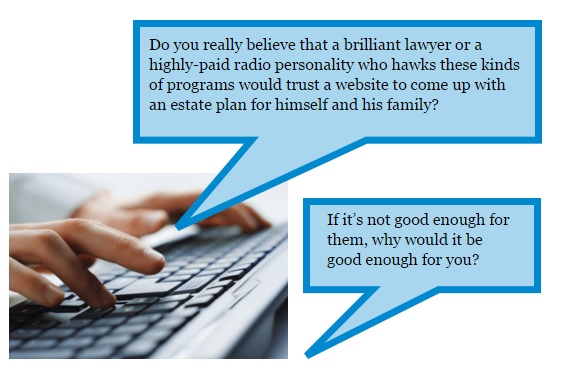
    You have seen the commercials. You have heard the radio ads. But before you go to a website to have your estate plan constructed by a computer program, be sure to ask yourself this:

    Generations Magazine- Hazardous Internet Documents - Image 21

    You may not have as large an estate as Mr. Fancyshmancylawyer or Mr. Radiobucks, but everything you own is everything you own, and it probably makes a difference to you whether it goes where you want it to go after you’re gone. It probably also makes a difference to you who will make decisions on your behalf if there is ever a time when you can’t make them yourself. Do you want your hand-picked decision-maker talking with your doctor as you lay there unable to speak, or are you willing to leave it to chance as to who steps up to the plate?

    You may respond, “You’re a lawyer who makes his living putting together estate plans for clients … of course you don’t like those legal websites. They cut into your bottom line.” Well, not really.

    Generations Magazine- Hazardous Internet Documents - Image 03A growing portion of my practice involves fixing estate plans prepared over the Internet. The problem with computer-driven estate plans is that in the real world, more often than not, they don’t work. An effective estate plan involves far more than a set of documents, even very well drawn documents that would stand up in any court in the land. For one thing, wouldn’t it be better to have an estate plan that will help you and your family stay out of court altogether? Going to court is not the end of the world, but it can be a royal pain. Most lawyers and judges are good, decent people. But does that mean that your estate plan should provide them with profitable employment? A much better approach is getting your plan right the first time, and then making sure that it continues to work according to your wishes in light of changes in your health, your stuff, the law, and the list of people you trust. If you can accomplish these things without court supervision, you will have reached estate planning nirvana.
    Bottom line: There is a lot of really good information on the Internet. There is also a lot of misinformation. Do you have the training and background to tell one from the other when it comes to putting your estate plan in order? If so, knock yourself out. If not, there is something to be said for working with a live professional instead of an impersonal website that cares more about your credit card authorization than about what happens to you and your stuff.


    Scott Makuakane, Counselor at Law
    Focusing exclusively on estate planning and trust law.
    Watch Scott’s TV show, Malama Kupuna
    Sundays at 8:30 p.m. on KWHE, Oceanic channel 11
    www.est8planning.com
    O‘ahu: 808-587-8227
    Email: maku@est8planning.com

    You have seen the commercials. You have heard the radio ads. But before you go to a website to have your estate plan constructed by a computer program, be sure to ask yourself this: You may not have as large an estate as Mr. Fancyshmancylawyer or Mr. Radiobucks, but everything you own is everything you…

  • Legal: Do You Have Four-Legged Children?

    Generations - 2014-02 - Four Legged Children - Image 01While I was growing up, we almost always had a dog (or two) in the house, and they always became treasured family members. You may have had the same experience, and you would not be alone if you have pets today that you consider to be your “children.” I know people who claim to prefer their kitties over their kiddies.
    So what happens to your four-legged family members if you become incapacitated, or if you die? Are you comfortable leaving their fate to chance, or do you want to take steps to provide for their well-being for the rest of their natural lives? Believe it or not, Hawai‘i law allows you to create trusts for your hairy household members.

    Generations - 2014-02 - Four Legged Children - Image 02Section 560:7-501 of the Hawai‘i Revised Statutes specifically allows you to create trusts “for the care of one or more domestic or pet animals.” You can even designate a human watchdog who will make sure that your intentions are carried out. In theory, there would be nothing to prevent your terrier’s trustee from making a quick stop at the local dog pound and then pocketing the trust assets that you had intended to be used for your poor pet. However, your Generations - 2014-02 - Four Legged Children - Image 03watchdog could whisk the trustee in front of a judge and make sure the trustee is held accountable for failing to honor your wishes. Of course, if you choose the right caretaker in the first place, none of this will be an issue.
    Generations - 2014-02 - Four Legged Children - Image 04But what if your two-legged children get jealous of your basset hound’s bequest? Is there a way for them to attack your trust? The short answer is “yes,” and if they can convince a judge that you have left “too much” for your toucan, the judge can reduce the amount in the trust to whatever amount is “enough” to provide adequately for the care, maintenance, health and appearance of the designated critter. In any event, if there is anything left when your pooch passes the pearly gates, you get to say where it goes.
    Generations - 2014-02 - Four Legged Children - Image 04Some pets have very long lifespans, such as certain birds, reptiles and fish. Your pet trust will not be subject to the rules that limit the lifespans of conventional trusts, so you can be sure that, as long as the trust assets hold out, there will be provisions for your pet.
    Another consideration that should go into your zoological estate plan is choosing who will provide the day-to-day care for your pets. Some animals bond closely with one human and are extremely persnickety about whose company they keep. When you are gone, someone could end up with a very irritable iguana. Hopefully, you have someone waiting in the wings to become the manager of your menagerie. Your passing is not a matter of “if” but “when,” and you should be brutally honest with yourself when choosing to bring a pet into your home and evaluating the future implications of that choice.


    Scott Makuakane, Counselor at Law
    Focusing exclusively on estate planning and trust law.
    Watch Scott’s TV show, Malama Kupuna
    Sundays at 8:30 p.m. on KWHE, Oceanic channel 11
    www.est8planning.com
    O‘ahu: 808-587-8227
    Email: maku@est8planning.com

    While I was growing up, we almost always had a dog (or two) in the house, and they always became treasured family members. You may have had the same experience, and you would not be alone if you have pets today that you consider to be your “children.” I know people who claim to prefer…

  • Legal: The Family Meeting

    Clients often ask me, “Do you do like they do in the movies, where the attorney sits with the family and reads the will after someone dies?” I tell them that I never do that after someone dies. Most clients then respond, looking puzzled, “You don’t?” I then explain that while I never do the “reading of the will,” I do suggest to every client that they consider, when appropriate, to engage in a meaningful discussion about the estate plan while everyone is alive and well.

    I feel that clients are not only asking me to help them to prepare a Will or Trust and leave a legacy, they are asking me to help speak for them when they no longer can. I hold this as a serious responsibility, as conversations can be difficult enough when everyone is here.

    Who should attend an estate planning meeting? You; the people you appointed to carry out your wishes; when appropriate, the beneficiaries; and your professional advisors, such as the financial advisor, estate planning attorney and accountant.

    What should be talked about during this meeting? First, you will want to explain your intent and meaning in establishing this plan. In other words, the “why” of the plan. Second, you should talk about how you would like to be cared for during periods of incapacity. And third, you will want to express your wishes for care should you find yourself in an end of life situation.

    Don’t believe everything you see in the movies. Even death takes planning.


    Stephen B. Yim, Attorney at Law
    2054 S. Beretania St., Hon.
    (808) 524-0251
    stephenyimestateplanning.com

    Clients often ask me, “Do you do like they do in the movies, where the attorney sits with the family and reads the will after someone dies?” I tell them that I never do that after someone dies. Most clients then respond, looking puzzled, “You don’t?” I then explain that while I never do the…

  • What Does Gender Have to Do With Retirement?

    When it comes to planning for retirement, women feel less prepared than men. That’s according to the New Retirement Mindscape® 2013 City Pulse index survey, commissioned by Ameriprise Financial. Only 38 percent of women surveyed say that they feel on track for retirement (or the remainder of retirement) compared to 46 percent of men.

    Women’s lack of confidence in the realm of retirement readiness may be tied in part to planning. Seventy-five percent of men surveyed reported that they’ve done at least some preparation for retirement, compared to 70 percent of women. And over half of men (55 percent) say they’ve contributed to a 401(k) plan, while only 47 percent of women claim they’ve done the same.

    What accounts for the gender divide? It may have to with the fact that women often face three unique financial hurdles on the road to retirement, including:

    1. Women often take time away from work to be caregivers. While caregiving is often the best option for a family’s situation, the reality is that spending time out of the workforce — whether to raise children or to provide care for a family member — can have a negative impact on one’s earning potential. Women (and men) who anticipate pausing their careers at some point in time to focus on other priorities should consider setting aside extra money at other times when they’re able to do so, in order to offset the loss of income.
    2. On average women live longer than men. This results in the need for additional retirement funds and increased health and long-term care costs. Yet, only 15 percent of women surveyed in the New Retirement Mindscape survey say that they’ve estimated the amount of money they’ll need to pay for healthcare during retirement, compared to 21 percent of men. It’s critical to create a plan for how you’re going to handle healthcare expenses.
    3. Women tend to be more conservative with investments. This may not be all bad, but defining and taking the appropriate amount of risk with your investment portfolio may be beneficial. Although, it’s important to have a balanced approach in your investments.

    Gender aside, baby boomers are feeling unprepared for retirement. With fewer years left to build up a nest egg, it’s important to focus on what you can control. Here are five steps you can take to feel more prepared for retirement:

    1. Think about what you want retirement to look like. Do you want to travel? Relocate? Spend more time with your grandkids? When you have a clear vision of retirement, it’s easier to determine what it will take to get there.
    2. Take advantage of employer-sponsored retirement plans. Make sure you’re maxing out your 401(k) contributions if you’re able. If you’re selfemployed, take the time to establish your own retirement plan.
    3. Consider purchasing long-term care insurance.
    4. Break down your expenses into two categories — essential and lifestyle. Determine if there’s anything you could forego on the lifestyle side.
    5. Focus on saving more, especially while you’re still working.

    Planning for retirement is complex and it’s not the same for everyone. Each person’s situation is unique. The key is to outline your goals for retirement, and then determining a path to get there. Consider meeting with a financial advisor who can help you with this.


    Michael W. K. Yee at (808) 952-1222 ext. 1240

    Michael W K Yee, CFP®, CFS®, CRPC®, is a Financial Advisor and CERTIFIED FINANCIAL PLANNER practitioner™ with Ameriprise Financial Services, Inc. in Honolulu, HI. He specializes in fee-based financial planning and asset management strategies and has been in practice for 25 years. To contact him, michael.w.yee@ampf.com, 808.952.1222 ext 1240, 1585 Kapiolani Blvd., Suite 1100 Honolulu, Hawai‘i 96814.
    Advisor is licensed/registered to do business with U.S. residents only in the states of Honolulu, Hawai‘i.
    1 The Money Across Generations IISM study was commissioned by Ameriprise Financial, Inc. and conducted by telephone by GfK in December 2011 among 1,006 affluent baby boomers (those with $100,000 or more in investable assets); 300 parents of baby boomers; and 300 children of baby boomers at least 18 years old. The margin of error is +/- three percentage points for the affluent boomers segment and +/- six percentage points for the parents and children of boomers segments.
    2 United States Department of Labor, Wage and Hour Division, Family and Medical Leave Act http://www.dol.gov/whd/fmla/
    Ameriprise Financial and its representatives do not provide tax or legal advice. Consult with your tax advisor or attorney regarding specific tax issues.
    Brokerage, investment and financial advisory services are made available through Ameriprise Financial Services, Inc. Member FINRA and SIPC.
    ©2012 Ameriprise Financial, Inc. All rights reserved.

    When it comes to planning for retirement, women feel less prepared than men. That’s according to the New Retirement Mindscape® 2013 City Pulse index survey, commissioned by Ameriprise Financial. Only 38 percent of women surveyed say that they feel on track for retirement (or the remainder of retirement) compared to 46 percent of men. Women’s…

  • Boo! Now Give Me Your Money

    Fear has always been a tool criminals use to get money from others. Whether it is created by holding a weapon to a cashier to get their compliance, or simply using a verbal threat against someone on the street to make him/her surrender their wealth, a robber wants his victim to believe they have to act quickly to avoid being harmed.

    The Office of the Prosecuting Attorney’s Elder Abuse Unit has seen fear also being used to scam seniors out of their money and assets. Unlike direct threats to their safety, however, many fear-based scams involve the illusion that the victim will lose their wealth, their security, or someone close to them if they don’t act quickly.

    One such scam that is occurring in Hawai‘i is the Distressed Relative Scam. This scam relies on the victim making a quick emotional decision, before they have time to verify the facts or to ask for advice from others. The victim will get a message, either a telephone call or an email, relating to them that a family member is in dire straights and money will solve the problem.

    An example of the charade can include a “doctor” calling the victim to inform them that their family member was injured while traveling and money needs to be sent immediately so that the loved one can be saved. Another has involved the con-man (or woman) claiming to be their grandchild or some other relation to the victim and informing them they were unlawfully arrested and need bail money to escape the mistreatment they are receiving in jail.

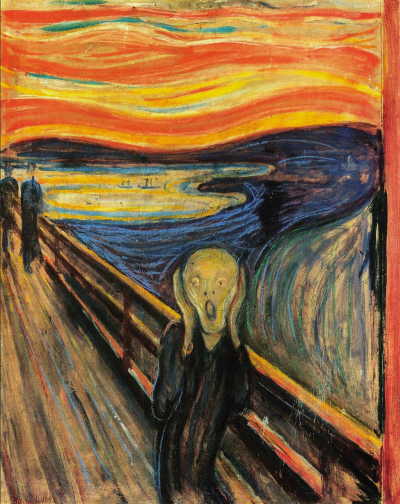
    Generations - 2014-02 - Boo Now Give Me Your Money - Image 01
    The Scream by Edvard Munch (1893)

    The perpetrator of this scam goes on to instruct the victim how they can either wire the money to them or tells them to get a Green Dot loadable charge card from Walgreens or Wal-Mart and put money into the card’s account and relay the account number on the back of the card to them.

    When hearing about this scam in the light of day, one can easily realize that there is something suspicious about the above scenarios. But as any parent or grandparent will tell you, the call they dread the most is one informing them that someone precious to them needs help. It is a message like this that will force them to panic and act before they think clearly about what is being said.

    Fear is also incorporated into other types of scams seniors encounter — such as when seniors receive a call from “the bank” saying that suspicious activity is occurring on their account, and then they are asked to give the caller their personal account information so that “the bank” can secure the account’s money. Additional scams include the lottery and sweepstakes scams featured in the December/January 2014 issue of Generations, and Sweetheart Swindles featured in the August/September 2013 issue.

    If you are ever contacted by someone and feel pressured to make a decision out of fear, then it is time to stop and verify the facts. This can be as easy as calling a relative to compare notes or calling Crime Stoppers at 808-955-8300.


    To Report Suspected Elder Abuse, call:
    Adult Protective Services
    808.832.5115
    ElderAbuse@honolulu.gov
    or visit www.ElderJusticeHonolulu.com.
    All reports are confidential.

    Fear has always been a tool criminals use to get money from others. Whether it is created by holding a weapon to a cashier to get their compliance, or simply using a verbal threat against someone on the street to make him/her surrender their wealth, a robber wants his victim to believe they have to…

  • Lotteries & Sweepstakes: You’re Not That Lucky

    Generations - 2014-12-01 - Lotteries and Sweetstakes - Image 01When Betty Lau (victim’s name changed) of Kaimuki opened her mail, she could not believe how lucky she was to find out that she won the $3-million Australian Lottery. The official looking letter explained that an unnamed company bought her a ticket as a promotional program and the enclosed Gold Credit Card from VISA contained the prize money. With the plastic card in hand, Betty felt confident this lottery was legitimate. Betty then read that the card had to be activated with a payment in order for her to gain access to the funds she had won. She was told, however, that any funds she paid would be put right back on the credit card. However, after making payment after payment, she received yet another notice that there was one more fee she had to pay in order for her to get access to the money. She had the feeling of playing a slot machine that kept showing “bar” “bar” cherry”— one more spin (or, in this case, payment) and she would win big. For the next three months, Betty sent more than $150,000 in an attempt to activate the card. It was only when she went through her entire savings account that she was forced to stop pursuing this fantasy.

    Unfortunately, the Elder Abuse Unit at the Prosecutor’s Office and the Honolulu Police Department are seeing the above scene being played out repeatedly in Hawai‘i. Letters, emails, and telephone calls are being received by seniors in increasing numbers. Each giving news that is too good to be true.

    These notices are official looking with impressive wording and says the victim must pay a small fee to receive their winnings. Some include credit cards, like in Betty’s case, while others include a real looking check. The victim is told to cash the check and send the money to another party to pay for the transaction/processing fees. The bank cashes the check without verifying it is real (because they are customer friendly after all). The victim then sends the money to the third party. When the bank discovers that the check was fake, they make the victim pay the cash back and threatens to call the police on the victim for passing a bad check.

    These scams have some things in common. Firstly, the notices state that the victim must act soon or the monies won will be put back into some sort of “general lottery fund.” Secondly, the letters advise the victims to not tell anyone they won so that they do not become victims of fraud. And finally, each of these letters ask for an advanced payment of fees in order to access the winnings.

    How can you prevent this from happening to you?

    Watch the news for information about recent scams.

    Review your bank statements for any unauthorized withdraws.

    Never rush into sending money to strangers. Talk to family, friends or financial advisors before taking action.

    Do not fill out contest entry forms. The entries are made into lists that can be bought by scam artists who can then contact you with accurate information you provided for the contest.

    And, finally, realize you are not that lucky to have won a contest you never entered.


    To Report Suspected Elder Abuse, call:
    Adult Protective Services
    808.832.5115
    ElderAbuse@honolulu.gov
    or visit www.ElderJusticeHonolulu.com.
    All reports are confidential.

    When Betty Lau (victim’s name changed) of Kaimuki opened her mail, she could not believe how lucky she was to find out that she won the $3-million Australian Lottery. The official looking letter explained that an unnamed company bought her a ticket as a promotional program and the enclosed Gold Credit Card from VISA contained…

  • Home Equity Into Retirement Income

    The long-struggling housing market is finally showing signs of recovery, giving many homeowners more equity in their properties. This is prompting more pre-retirees to consider if, and how, home equity can be turned into a source of cash to help fund their retirement.

    Home equity represents one of the biggest assets for many Americans. However, there are risks in assuming that your home’s equity will be a guaranteed source of income in retirement. For starters, home equity, like any investment, is subject to the fluctuations of the market and may have tax consequences. Also, you will always need a place to live, so you can’t assume that the full value of a home is at your disposal. Remember that the primary function of your home is to provide a roof over your head, and using equity to fund retirement requires careful planning. Here are three primary options:

    • Home Equity Lines of Credit (HELOC): A HELOCS (second mortgage) is a reasonable option for an employed individual, but it may be less practical for someone in retirement. HELOCs need to be repaid, and using the proceeds from a home equity loan to help fund retirement often means taking on interest costs in order to generate that income. It’s important to note that an individual puts a lien on their home by taking a HELOC, and risks losing it should he or she fail to repay under the terms of the loan.
    • Reverse Mortgage: A popular alternative is a reverse mortgage. This allows a homeowner to tap into the home equity while still occupying it. A reverse mortgage provides payment to homeowners for the bulk of the value of their homes via a lump sum, a line of credit or periodic payments. In essence, this is a loan to the homeowner paid back when the house is sold at some future date. However, interest accrues throughout the duration of the loan and upfront fees apply, so it can be expensive.

    A standard reverse mortgage, also called a Home Equity Conversion Mortgage, charges a 2 percent mortgage insurance premium on the full value of the home. The government now offers a lower cost “Saver” loan with a mortgage insurance premium of just 0.01 percent of the home’s value, but applying a higher interest rate. Over time, the combination of fees and interest charges can significantly deplete the value of the home’s equity.

    Reverse mortgage applicants must be at least 62 years old. The older a retiree is, the more he or she can receive from the home’s equity. Understanding the complicated terms of a reverse mortgage before signing on the dotted line is crucial.

    Selling & Downsizing: The other way to tap a home’s equity is to sell it. Many retirees are ready to “downsize” or to buy or rent a smaller residence. If the market is right, they can sell their existing home, buy a new place and have equity leftover to add to their retirement nest egg.


    Michael W. K. Yee at (808) 952-1222 ext. 1240

    Michael W K Yee, CFP®, CFS®, CRPC®, is a Financial Advisor and CERTIFIED FINANCIAL PLANNER practitioner™ with Ameriprise Financial Services, Inc. in Honolulu, HI. He specializes in fee-based financial planning and asset management strategies and has been in practice for 25 years. To contact him, michael.w.yee@ampf.com, 808.952.1222 ext 1240, 1585 Kapiolani Blvd., Suite 1100 Honolulu, Hawai‘i 96814.
    Advisor is licensed/registered to do business with U.S. residents only in the states of Honolulu, Hawai‘i.
    1 The Money Across Generations IISM study was commissioned by Ameriprise Financial, Inc. and conducted by telephone by GfK in December 2011 among 1,006 affluent baby boomers (those with $100,000 or more in investable assets); 300 parents of baby boomers; and 300 children of baby boomers at least 18 years old. The margin of error is +/- three percentage points for the affluent boomers segment and +/- six percentage points for the parents and children of boomers segments.
    2 United States Department of Labor, Wage and Hour Division, Family and Medical Leave Act http://www.dol.gov/whd/fmla/
    Ameriprise Financial and its representatives do not provide tax or legal advice. Consult with your tax advisor or attorney regarding specific tax issues.
    Brokerage, investment and financial advisory services are made available through Ameriprise Financial Services, Inc. Member FINRA and SIPC.
    ©2012 Ameriprise Financial, Inc. All rights reserved.

    The long-struggling housing market is finally showing signs of recovery, giving many homeowners more equity in their properties. This is prompting more pre-retirees to consider if, and how, home equity can be turned into a source of cash to help fund their retirement. Home equity represents one of the biggest assets for many Americans. However,…

  • Is Physician-Assisted Suicide Legal in Hawaii?

    A large, well-funded national organization has been taking out print ads and airing TV commercials that claim that doctors in Hawai‘i are providing lethal doses of medication to individuals who desire “aid in dying.” According to the ads and commercials, this is perfectly legal because of a newly discovered loophole inHawai‘i law.

    As it turns out, however, the ads and commercials ignore what Hawai‘i’s chief law enforcement officer, attorney general David Louie, has said about this topic. In an opinion letter dated December 8, 2011, Louie addresses:

    • whether section 453-1 of the Hawai‘i Revised Statutes (the supposed newly discovered loophole) authorizes a physician to assist a terminally ill patient with dying
    • whether any criminal laws prohibit “aid in dying”

    Louie opines that the loophole being touted in favor of physician-assisted suicide simply allows doctors to prescribe unconventional “remedial agents or measures” (i.e. medication or treatment intended to make the patient better — or at least to provide pain relief and comfort), not cause the patient’s death. In the attorney general’s view, the law clearly does not allow doctors to prescribe lethal doses of medication.

    As to the second question, Louie opines that physician-assisted suicide would constitute the crime of manslaughter. However, proving that the crime had been committed would involve convincing a jury that the physician intended for the patient to commit suicide, and that the lethal medication prescribed by the physician accomplished its intended task. As we all know, proving that a crime has been committed is not necessarily an easy task. But the fact that a crime is difficult to prove does not mean that no crime was committed. Obviously, any physician who follows interpretation of Hawai‘i law urged in the current advertising blitz could be in for serious trouble.

    So don’t be fooled by the commercials and ads. Our existing hospice and palliative care (alleviating pain) physicians and services do a wonderful job of assisting the terminally ill and their families face death. There are legitimate and compassionate ways of dealing with end of life issues that do not involve suicide or raise the prospect of euthanasia.

    For more information, or if you would like a copy of the Attorney General’s opinion, email info@est8planning.com.


    Scott Makuakane, Counselor at Law
    Focusing exclusively on estate planning and trust law.
    Watch Scott’s TV show, Malama Kupuna
    Sundays at 8:30 p.m. on KWHE, Oceanic channel 11
    www.est8planning.com
    O‘ahu: 808-587-8227
    Email: maku@est8planning.com

    A large, well-funded national organization has been taking out print ads and airing TV commercials that claim that doctors in Hawai‘i are providing lethal doses of medication to individuals who desire “aid in dying.” According to the ads and commercials, this is perfectly legal because of a newly discovered loophole inHawai‘i law. As it turns…

  • Are You ‘Good to Go?’

    We all know death is a natural part of life and something we will all experience. But have you thought about how you want to be treated during your final days? How you would like to die?

    Though it’s not an easy topic, and most of us avoid thinking about it, consider giving your death some thought this holiday season. What better way to start the New Year than with a resolution to complete your advance healthcare directive and talk to your family about what you want at the end of life?

    In fact, there is a growing movement in Hawai‘I and the nation toward considering how we want to die and sharing those wishes with doctors, caregivers and loved ones. Increasingly, people feel everyone deserves to make their own personal decisions for dying with comfort, dignity and control.

    Compassion & Choices Hawai‘i is part of this movement. They help people receive state-of-the-art care and the full range of options at the end of life, including disease-specific treatment, palliative care, hospice, avoidance of unwanted medical treatment and access to aid in dying, which is the option to advance the time of death if suffering becomes unbearable.

    How do you get the conversation started?

    After many attempts to engage family members, one Compassion & Choices client set her holiday table with advance directive forms at every place setting and announced, “Nobody gets dinner until these are filled out.” Now that’s some tough turkey!

    And while the paperwork is important, the essential thing is to get the conversation going. Try starting with, “If one of us ever had to make decisions about your treatment because you couldn’t, it would be much easier if we knew what you really want.” Then ask the following:

    • Would you want life support if you have a terminal illness? What if you’re in a permanent coma? What if you have a chronic illness such as Alzheimer’s disease?
    • Do you always want to know the truth about your condition? About treatment options and their odds of success? And what does “success” mean to you and quality of life?
    • What will be important to you when you are dying? No pain? Hold on as long as possible? Family members present? What are your priorities?
    • Would you want to be in a nursing home if your condition warranted?

    Compassion & Choices has a free Good-to-Go Toolkit to guide your conversation and document the results at www.CompassionAndChoices.org/advance-directive.

    Compassion & Choices’ End-of-Life Consultation is a free service. Professional consultants listen to each unique situation and provide information, emotional support and patient advocacy as people navigate complex choices about terminal illness or the dying process.

    For more information, free consultation, access to the Good-to-Go Toolkit and much more, call 1-800-247-7421 or visit www.CompassionAndChoices.org/hawaii.

    We all know death is a natural part of life and something we will all experience. But have you thought about how you want to be treated during your final days? How you would like to die? Though it’s not an easy topic, and most of us avoid thinking about it, consider giving your death…