Category: Wisdoms

  • Put Your Voice Into Your Estate Plan

    Singing has always been a passion of mine — with my brothers, in choirs or in the shower. In choir, when the director handed out new music, I remember looking at the black notes on the white sheets of paper and thinking that the music made no sense, and it’s going to be really boring to sing.

    As our choral group rehearsed and blended in harmony, the melody would always come to life and become a beautiful story in song—even more so as I connected more with the composer of the music, and the meaning and emotion the author intended to convey.

    Everyone’s voice is unique, textured and lovely in its own way. When everyone sings in harmony, it makes the song exponentially more beautiful.

    An estate plan has been regarded “as the sole, authentic voice of a man who is dead.” However, much like that sheet of paper with notes on it during the first day of choir practice, if left as a template legal document, without the maker breathing life (voice) and personal meaning into it, the legal document will remain sterile, sometines rendering it almost meaningless.

    What is at risk in this case is family harmony.

    Family members will apply their own song and lyrics to the document in the absence of the ma-kers’s voice, rather than being able to hear and honor the loved one’s story.

    When you work with your attorney to establish or update your plan, to ensure harmony, please remember to make sure to incorporate your unique, textured and dynamic solo voice.


    Stephen B. Yim, Attorney at Law
    2054 S. Beretania St., Honolulu HI 96826

    808-524-0251  |  www.stephenyimestateplanning.com

    Put Your Voice Into Your Estate Plan by Stephen B. Yim, Attorney at Law from the August-September 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Drive-By Victims: Homeless Seniors

    Charlie (not his real name) is a 68-year-old veteran who lives with several hundred people under the viaduct near Honolulu International Airport. This large group of homeless people (or as law enforcement calls them, “residentially challenged”) has formed a community. Unfortunately, as in most communities, there are persons who prey on seniors like Charlie.

    One day, Charlie was sitting near his belongings when a camp member approached him, demanding his flashlight. When Charlie refused, the man hit him on the head with enough force to knock him down and create a three-inch gash.

    Charlie was my introduction into the homeless senior victim arena. In 2008, when I was creating the elder abuse team at the Prosecutor’s Office, I imagined my victims to be found in care homes, relatives’ homes, or their own homes. Little did I realize that a large portion of my cases happen where the victims have no homes at all. Throughout the years, I was reminded of this fact over and over again.

    My first murder case involved a homeless senior looking for shelter at a church in Mānoa. Unfortunately, he found another homeless man instead, David Orpin, who beat him to death for “invading” his territory. Another particularly violent case happened (again, near the airport viaduct) when a homeless man rode his bicycle up to a pair of senior women who were using the overpass for shelter. The bicyclist made obscene comments and exposed himself. When the younger woman ran for help, the bicyclist brutally assaulted and raped the 75-year-old.

    Some of my more violent cases occur in places open to the public that most of us just drive by without notice. Our attention is only drawn when homeless encampments mar the scenery, causing many to complain about how the government needs to do something about “them” to remove the homeless from our sight. Unfortunately, removing the homeless from sight will only create an environment that will breed more crimes against our elderly homeless. Now, however, when you see the tents and cardboard box shelters lining the beaches and walkways of Hawai‘i, you will know that they house not only homeless seniors, but the criminals who prey on them.

    Volunteering or donating to nonprofits that assist the homeless are good ways to help people down on their luck and to protect them.


    To report suspected elder abuse, contact the Elder Abuse Unit at
    808-768-7536 | ElderAbuse@honolulu.gov
    www.ElderJusticeHonolulu.com

    Drive-By Victims: Homeless Seniors by Scott Spallina, Senior Deputy Prosecuting Attorney from the August-September 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Vacation With Your Important Papers

    Hauling a massive three-ring binder or a file folder with you when you travel is imprac-tical. However, there are times when having 
your estate planning documents at your fingertips can be helpful. If you or someone close to you should experience a health emergency and can’t make decisions, how do you prove who has the authority to step in as “substitute decision maker?” Wouldn’t it be ideal to have immediate access to your advance healthcare directive and possibly other estate planning documents as well? The good news is you can.

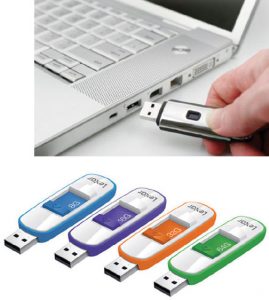
    Generations Magazine - August-September 2016 - Vacation-Important-Papers_image1One substitute for that great big binder is a USB, “thumb” or “jump” drive. It is a thumb-sized piece of hardware that plugs into almost any computer (iPads excepted) that will store more electronic documents than you will ever need it to hold. At a bare minimum, you will want store a copy of your advance directive and your HIPAA authorization (the document that gives medical providers your permission to talk to your decision maker), but you might also want other documents, such as your durable power of attorney. The downside to this technology is that it is a piece of non-waterproof hardware that can be lost, or stolen and misused.

    Another solution is to subscribe to a service that gives you online access to your documents. Two companies that provide this service are:

    1) Legal Directives 866-363-4894, www.legaldirectives.com

    2) DocuBank 866-362-8226, www.docubank.com

    Both companies will keep your advance directive and HIPAA authorization on file and give you the ability to look at them online and print them out, or have them faxed by way of an automated system to any location. The way you access the system is by following the instructions on a credit card-sized plastic card that you are issued. This is a great solution while you are in your hometown, as well as well as when you are on the road. The major catch is that you need to have your card with you when you go to the emergency room or otherwise seek treatment.

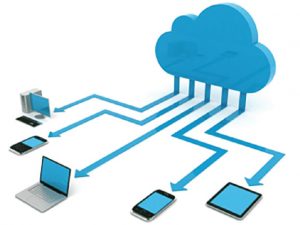
    Generations Magazine - August-September 2016 - Vacation-Important-Papers_image2Yet another option is Internet technology that allows you to store your estate planning documents in the “cloud” and access them from any computer or laptop (including your iPad) whenever you need to, and from wherever you happen to be at the time. One example is called Cubby (www.cubby.com), but there are others on the market. When you are a Cubby subscriber, you can create a secure link that you (or your kids or your financial planner) can use to access your estate planning documents 24/7. This can be a very helpful solution in a variety of contexts — not just medical emergencies.

    Of course, all of these technologies require access to a computer, a telephone and/or a fax machine, and may require Internet access.

    If your travels take you deep into the jungles of Borneo or to the summit of Mt. Everest, you may need to do things the “old-fashioned” way and carry paper copies in a waterproof container.


    SCOTT MAKUAKANE, Counselor at Law
    Focusing exclusively on estate planning and trust law.

    O‘ahu: 808-587-8227  |  maku@est8planning.com
    www.est8planning.com

    Vacation With Your Important Papers by Scott A. Makuakane, Counselor at Law, Est8Planning Counsel LLLC from the August-September 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Giving Retirement Assets

    Americans own trillions of dollars in qualified pension plans, profit sharing plans, 401(k)s, 403(b)s, SEPs and IRAs. Congress never meant for these plans to be passed tax-free to heirs. They are considered “income in respect of decedent or IRD.”

    Someone has to pay tax on these assets. By leaving them to someone other than your spouse, your heirs may pay significant taxes on this inheritance. Even if you do not have a taxable estate, the tax rate for your heirs on these assets could be quite substantial.

    CHARITABLE BEQUEST

    Consider gifting IRD assets, because charities are tax-exempt and will not pay taxes on retirement assets. Leave heirs assets such as your home or stocks that step up to fair market value when you pass away, leaving little or no tax to pay.

    CHARITABLE GIFT ANNUITY OR CHARITABLE REMAINDER TRUST

    Some use IRD assets to fund a charitable gift annuity that will benefit a family member with lifetime fixed payments. Typically, this type of gift is used by older beneficiaries in exchange for fixed, tax-advantaged payments.

    Funding a charitable remainder trust with IRD assets creates a tax-advantaged charitable legacy for your heirs, while lessening their tax burden. The trust will pay income over years, spreading out their tax burden. At the end of the trust, any remaining principal will go to the charity.


    National Kidney Foundation of Hawaii
    808-589-5976 | jeff@kidneyhi.org
    For Planned Giving: www.kidneyhawaii.org
    Main: www.kidneyhi.org  |  www.kidney.org

    Giving Retirement Assets by Jeffrey B. Sisemoore, JD, National Kidney Foundation of Hawaii from the August-September 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Medicare Identity Theft

    SPECIAL FEATURE Medicare-Identity-Theft_image1Medicare Identity Theft is a serious and growing problem that impacts the lives of millions of seniors every year. A variety of reasons, including the expansion of technology and the Internet, allow personal information to be stolen and sold worldwide. Furthermore, the sheer magnitude of Medicare provides both incentive and opportunity for thieves to take advantage of the program. Medicare serves 46 million beneficiaries, who are primarily seniors, and expends $375 billion annually. Because it is so large and complex, with thousands of health care providers submitting millions of claims daily, Medicare is difficult to oversee. As a result, $68 billion is estimated to be lost to fraud annually.

    The loss of a senior’s Medicare card or Social Security card (Note: both numbers are the same) immediately puts the senior at risk. While Social Security will replace the Medicare or Social Security card, it will not issue a new number. When this valuable identification falls into the wrong hands, the senior will be at risk of being victimized for the rest of his or her life.

    What risks might the senior be exposed to from identity theft? Theft and misuse of a beneficiary’s Medicare number can lead to false claims being filed under that number and can impact the beneficiary with staggering medical bills, maxed-out benefits and compromised medical history records.

    In a report about medical identity theft, Pam Dixon, Executive Director of the World Privacy Forum (WPF) pointed out, “Victims of medical identity theft may receive the wrong medical treatment, find their health insurance exhausted, and could become uninsurable for both life and health insurance coverage.” She warned, “Changes made to victims’ medical files and histories can remain for years and may not ever be corrected, or even discovered, which can have deadly consequences.”

    A different blood type, incorrect reports of substance abuse, someone else’s lab test results, wrong history of illnesses — think about the serious consequences any one of these could have for the victim of medical identity theft.

    What should seniors do to protect themselves from shattering financial loss and personal harm? The primary protection is to exercise extreme vigilance and caution on all matters relating to Medicare and personal identification, such as Medicare number, Social Security number, birth date, birthplace, and mother’s maiden name. Here are some precautions that will minimize risk:

    • Keep a record of doctor visits, hospital visits and medical supplies and equipment purchases. The Senior Medical Patrol (SMP Hawai‘i) has a Personal Health Care Journal for that purpose. Call 586-7319 or 1-800-296-9422 for a copy.
    • Check the Medicare Summary Notice (MSN) or Explanation of Benefits (EOB) for possible errors. If there is a mistake in the Medicare statement or another billing issue, call SMP Hawai‘i for assistance. All that may need to be done is to call the provider to correct the error. If concerns remain, SMP Hawai‘i staff and certified volunteers will assist.
    • Always safeguard your Medicare card. Be careful not to give out the number to anyone questionable.
    • Do not accept money or free gifts, products, or services in exchange for the Medicare number.
    • Beware of persons that claim to be from the government and ask for personal information or money. Try to get their name and phone number. Report the contact to SMP Hawai‘i.
    • Be informed about beneficiary’s rights under Medicare, including access to medical records, statements of services received, and appeals of unfavorable decisions.

    In summary, Medicare identity theft is a real and growing threat to seniors’ wellbeing and Medicare’s sustainability. Seniors are the best front-line defense to detect, prevent, and report Medicare identity theft. To perform that role, they need to keep informed and be proactive.

    “Who is the Senior Medicare Patrol (SMP Hawai‘i)?”

    In 1997, through Public Law 104-208, the U.S. Administration on Aging established 12 grant-funded demonstration projects to recruit and train retired professionals to identify and report error, fraud and abuse related to Medicare. Hawai‘i received one of the original 12 grants, and named its Senior Medicare Patrol project, “SageWatch.” Now, “SMP Hawai‘i,” the project is based in the State Executive Office on Aging.

    SMP Hawai‘i has volunteers on Kaua‘i, O‘ahu, Maui, Moloka‘i and Hawai‘i. The volunteers engage in educational outreach about Medicare fraud by disseminating information at community events and group presentations. Currently, SMP Hawai‘i is conducting a statewide media campaign to recruit volunteers and to reach Cantonese, Ilocano, Tagalog and Vietnamese populations in Hawai‘i. You may have seen SMP ads in Generations Magazine and RSVP newsletters and heard SMP radio announcements on KNDI, ESPN 1420/1500, and Hawai‘i Public Radio. In the works, is a volunteer recruitment public service announcement for TV.


    For more information, contact Senior Medicare Patrol (SMP) program:
 www.smpresource.org | 808-586-7281 | 1-800-296-9422 (toll-free)

    For presentations, resource materials or a volunteer application packet, call: 808-586-7319
     

    Medicare Identity Theft is a serious and growing problem that impacts the lives of millions of seniors every year. A variety of reasons, including the expansion of technology and the Internet, allow personal information to be stolen and sold worldwide. Furthermore, the sheer magnitude of Medicare provides both incentive and opportunity for thieves to take…

  • Paying Yourself in Retirement

    The most important part of your retirement plan is the monthly income you set aside for essential and lifestyle expenses. More retirees — especially those who don’t have a pension — will have to rely on a combination of income sources. Here are some tips to consider as you design your plan.

    Create a plan

    A recent Ameriprise Financial study found that more than half of the country’s pre-retirees feel overwhelmed and anxious about their impending retirement, and worry that they will run out of money. However, pre-retirees with a retirement income plan are more likely to feel confident about their financial future. You, too, can take action to help lessen fears about the unknown.

    Project your expenses

    Cut yourself a “reality check” that covers your monthly bills. Tally your expected retirement expenses. Next, consider extras in your retirement lifestyle, including travel, visiting grandkids, starting a small business and community charity work. Expenses after retirement are personalized and may vary over time; make sure your budget supports your goals.

    Make a list and check it twice

    Will you have multiple potential sources of income available in retirement? List all your assets and income streams, such as Social Security, stocks, bonds, Certificates of Deposit (CDs) or annuity income. Round up your IRAs or 401(k)s and potentially consolidate accounts if it makes sense.

    Understand the impact of taxes

    Once you hit retirement, taxes may impact you differently. To avoid surprises, ensure that taxes are a part of your retirement income plan. To avoid tax penalties, calculate Required Minimum Distributions (RMDs) — the minimum amount of money you must withdraw from your retirement accounts each year after age 70½. Talk to your tax advisor about RMDs and other strategies to help minimize your retirement tax bill.

    Give yourself flexibility

    Ensure you have a diversified, balanced portfolio to weather unexpected events that may occur in retirement. Gear some investments for generating stable income — those less likely to change in value–and others for easy conversion to emergency cash. For maximum flexibility, identify the assets that you plan to draw down first.

    Time is on your side

    The sooner you start thinking about how to pay yourself in retirement, the better off you’ll be. Tackle tasks one at a time and allow yourself the luxury of being able to carefully think through your retirement goals and financial scenarios.

    Work with a professional

    Consult a financial professional with experience creating reliable, lasting income strategies in retirement.


    MICHAEL W. K. YEE, CFP
    
1585 Kapiolani Blvd., Ste. 1100, Honolulu
    808-952-1222 ext. 1240  |  michael.w.yee@ampf.com

    Michael W. K. Yee, CFP®, CFS®, CLTC, CRPC®, is a Financial Advisor, Certified Financial Planner ™ practitioner with Ameriprise Financial Services, Inc. in Honolulu, Hawai‘i, with Na Ho’okele Financial Advisory Team, a financial advisory practice of Ameriprise Financial Services, Inc. He offers fee-based financial planning and asset management strategies and has been in practice for 29 years.

    The Pay Yourself in Retirement study was created by Ameriprise Financial utilizing survey responses from 1,305 Americans ages 55 to 75 with investable assets of at least $100,000. The online survey was commissioned by Ameriprise Financial, Inc., and conducted by Artemis Strategy Group from November 16–22, 2015.
    Investment advisory products and services are made available through Ameriprise Financial Services, Inc., a registered investment adviser.
    Ameriprise Financial Services, Inc. Member FINRA and SIPC

    © 2016 Ameriprise Financial, Inc. All rights reserved. File #1438828

    Paying Yourself in Retirement by Michael W. K. Yee, Financial Advisor and Certified Financial Planner from the June-May 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Will You Leave a Legacy?

    Generations Magazine -0WillYouLeave_image1Giving is a tradition in Hawai‘i, extending as far back as the original ancestors and including the many people and cultures that have since arrived on our shores. Chances are, you or someone you know has been a beneficiary of the generosity of others; chances are you also have given to people and causes that are important to you. And because of giving, our community thrives, lives are made better and a sense of ‘ohana is nurtured.
    A legacy is a special form of giving, usually created as part of the estate planning process when wills and trusts are used. A legacy can also be beneficiary designations for retirement plans, life insurance and similar financial tools. A legacy is a way of leaving a footprint on your world for the betterment of those who will follow.

    Examples of famous legacies in Hawai‘i include the Kapi‘olani Medical Center for Women and Children, founded by Queen Kapi‘olani, and the Honolulu Museum of Art, founded by Anna Rice Cooke.

    The mission of the National Kidney Foundation of Hawaii is to fight chronic kidney disease in Hawai‘i through many innovative programs and services. The foundation is pleased to join with the Hawai‘i Community Foundation to encourage all of us to make our own legacies. Find more information at www.hawaiicommunityfoundation.org or www.kidneyhi.org and select the “Gift Planning” button.


    National Kidney Foundation of Hawaii
    808-589-5976  |  jeff@kidneyhi.org
    
For Planned Giving: www.kidneyhawaii.org
  |  Main: www.kidneyhi.org  |  www.kidney.org

    Will You Leave a Legacy by Jeffrey B. Sisemoore, JD, National Kidney Foundation of Hawaii from the June-May 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Sycamore Row

    I recently finished reading the John Grisham novel Sycamore Row. Filled with intrigue, suspense and surprises around every corner, it deserves its No. 1 New York Times Bestseller status as a fiction novel.

    As the story opens, Seth Hubbard hangs himself from a Sycamore tree. Before he does, he composes a handwritten will and sends it to Attorney Jake Brigance, instructing him to make sure that it’s enforced. In the document, Seth leaves 90 percent of his estate to his housekeeper and disinherits his children.

    Because all Seth’s children and grandchildren hire lawyers who all try to discredit the will, Jake finds himself embroiled in a big, controversial trial. Over the next 600-or-so pages, Jake tries to find out why Seth disinherited his children and gives almost everything to the housekeeper.

    Greed and family conflict make great fiction, but sadly, many families find themselves in similar real-life battles.

    Author Simon Sinek wrote a book entitled Start with Why. If Seth had written his “reasons why,” Sycamore Row would be about 10 pages long — and very boring.

    We must, as estate planners, do a better job of encouraging clients to pass on assets with clear intention. Our goal is to help clients clearly define their wishes in anticipation of a time when they may no longer be able speak for themselves.

    Then, we can leave the mystery, intrigue, conflict and suspense to Grisham, and then focus on families and honoring real-life intentions.


    STEPHEN B. YIM, Attorney at Law
    2054 S. Beretania St., Honolulu 96826
    808-524-0251  |  www.stephenyimestateplanning.com

    Sycamore Row by Stephen B. Yim, Attorney at Law from the June-May 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Endowment Gift Keeps on Giving

    The very lifeblood of your favorite charity is the annual donations that come from regular donors. When a regular donor passes away or stops giving, it may be difficult for the charity to replace the needed income stream. One way to avoid this is for faithful donors to create lifetime endowments or to leave endowments in their estate plans. It doesn’t take an unusually large gift to make a difference.

    If you annually contribute $100, then putting $2,000 in an endowment is enough for that level of annual giving to continue in perpetuity. This ratio holds up no matter how much you give each year. An endowment of 20 times an annual gift should allow for the same contribution to continue each year for long after you pass away or stop giving.

    Contact your favorite charity for ideas about how to multiply the benefits of your gift — both for you at tax time and for the charity. If the charity is not geared up to manage endowments, you can create an endowment quickly and easily, with very few administration fees. Organizations like the Hawai‘i Community Foundation (which has offices in Honolulu, Waimea, Hilo, Li¯hue and Kahului, and can be found online at www.hawaiicommunityfoundation.org) or the Hawai‘i chapter of the National Christian Foundation (808-524-5678) will assist you.

    Creating an endowment fund through an established charitable foundation can also enable you to make gifts to multiple charities. When you create your endowment fund, your gift is immediately tax-deductible (within limits prescribed by the Internal Revenue Code) because the foundation is itself a tax-exempt entity. You can then direct the foundation to send checks to all or any of the charities you support. You can tell the foundation to let the charities know that the gifts came from you or to issue your gifts anonymously.

    Moreover, your endowment gift does not have to be cash. If you have stock or real estate that you are considering selling in order to make charitable gifts, you can put those assets directly into your endowment fund and let the foundation sell them. If you sell the assets yourself before you make your gift, you may have to report capital gains and pay taxes on those gains. Your net gift will be the amount of your sales proceeds minus sales costs and taxes.

    On the other hand, if you give the assets to the foundation, the foundation can sell them and put the net proceeds into your endowment fund (with no taxes on capital gains), and your potential deduction will be the full fair market value of the gifted assets. If you give more than the law allows you to deduct in any one year, you can “carry forward” your gift and deduct a portion of it over each of the next five years or until you have fully deducted your gift, whichever comes first.


    SCOTT MAKUAKANE, Counselor at Law
Focusing exclusively on estate planning and trust law.
    Watch Scott’s TV show, Malama Kupuna
Sundays at 8:30pm on KWHE, Oceanic Channel 11
    www.est8planning.com
  |  O‘ahu: 808-587-8227  |  maku@est8planning.com

    Endowment Gift Keeps on Giving by Scott A. Makuakane, Counselor at Law, Est8Planning Counsel LLLC from the June-May 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Stop Being an Easy Victim

    I don’t like to work. I have said this for years in presentations around the island. People laugh, thinking I am joking. I am not.

    I am on-call 24 hours a day, seven days a week. When a crime occurs and the victim is 60 years of age or older, the police page me and I drive down to the station to review the evidence. It is not fun there. They don’t have doughnuts and the detectives aren’t as funny as those on “Barney Miller.”

    I have spent more than one holiday sitting at a gray metal desk reading police reports and eating old Halloween candy. But perhaps the biggest reason I don’t like being at the police station is that often, the crimes I am reviewing could have been easily avoided.

    For example, a great percentage of the stolen car cases our office prosecutes are a result of seniors leaving the keys in the vehicle, or leaving the car running as they pop back into the house for something they forgot, or running into a store for a quick errand, only to find their car gone when they return.

    Speaking of cars, please stop leaving credit cards and checkbooks in them. A drug addict’s favorite place to go shopping is in a parking lot. A left-behind wallet, purse or checkbook is a big payday for someone feeding a habit.

    Also, lock the doors to your home. You don’t live in Mayberry with Aunt Bee. Many burglaries have been committed by persons who just open an unlocked door. Frequently, the criminal will not care whether or not someone is home or what time of the day or night it is. Simply securing your house deters unwanted strangers.

    Speaking of strangers, don’t let them in! Many identity thefts, burglaries and assaults start with a homeowner letting in a person they don’t know. The man who says he is from the utility company and needs to check something — do you really know where he is from? Direct anyone needing to use your restroom to the nearest public facility.

    My cautions may sound harsh; I have heard that because we live on a small island, aloha is a way of life. If that were true for everyone, tell me why crimes affecting the elderly have increased over 300 percent since I started the Elder Abuse Unit? If you don’t want to take simple steps to prevent yourself from being a victim of a crime, do it for me. I am tired of eating stale candy.


    To report suspected elder abuse, contact the Elder Abuse Unit:
    808-768-7536  |  ElderAbuse@honolulu.gov  |  
www.honoluluprosecutor.org

    Stop Being an Easy Victim by Scott Spallina, Senior Deputy Prosecuting Attorney from the June-May 2016 issue of Generations Magazine, Hawai‘i’s Resource for Life

  • Make Your Dream Home Come True

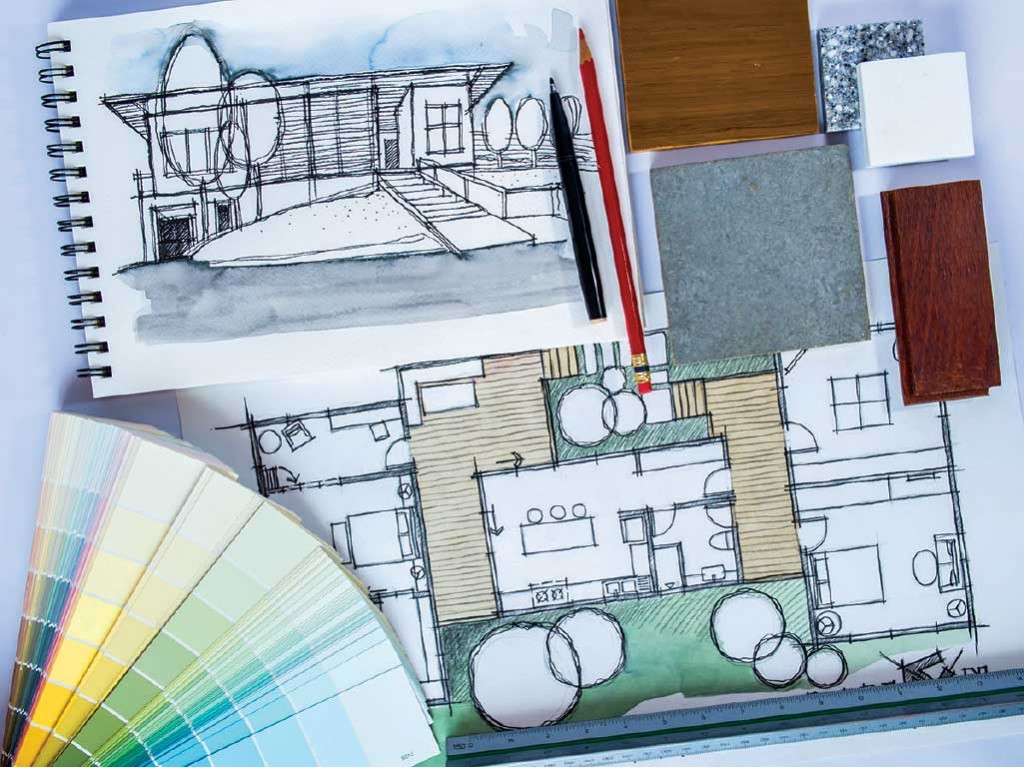
    Generations Magazine - Wisdoms - Make Your Dream Home Come True

    You have the resources to turn your house into the dream home you’ve always wanted. Now, what? Here are some tips to help you plan your remodel.

    Compile your wish list.

    Prioritize your list by identifying what projects and features are important to you and your lifestyle. Use your list to determine the scope and budget of your remodel. Consider breaking your project into phases to make it more manageable if you have a big list.

    Select your contractor — carefully.

    Personal and professional referrals can help you narrow your search for a quality contractor. Find someone you trust professionally, who understands your taste, budget and lifestyle. Make sure your contractor has the bandwidth of employees or subcontractors to complete the work in a timely fashion. Be sure insurance is in place.

    Set your budget, with contingencies.

    Remodeling projects — especially those involving older homes — often reveal surprises that require you to re-evaluate your budget and timeline. For best success, allocate 15 to 20 percent of the project estimate for contingencies. If the project nears completion with your contingency budget still in place, you could upgrade the finishing touches.

    Review the contract before signing.

    Once you’ve agreed on the scope of work , timelines and how contingencies will be handled, your contractor should provide a detailed contract that clearly documents key features or unique aspects of the project. Check that it includes a lien waiver clause, which ensures subcontractors and suppliers will have been paid before you make the final payment.

    Understand how you’ll pay.

    Most contractors require a down payment to get your project rolling. The remaining budget is usually paid in regular installments or as major work is completed (i.e., electrical work, plumbing). The difference between these options can be significant. Review your budget with a financial professional who can help you manage your cash flow.

    Keep remodeling receipts on file.

    Energy efficiency improvements resulting from your remodel may be eligible for tax credits through 2016. And if you sell your home down the road, your remodeling costs may help reduce your capital gains tax. To be eligible, you must show that these expenses enhance the value of your home and are not for general upkeep.


    MICHAEL W. K. YEE, CFP
    1585 Kapiolani Blvd., Ste. 1100, Honolulu
    808-952-1222 ext. 1240 | michael.w.yee@ampf.com

    Michael W. K. Yee, CFP®, CFS®, CLTC, CRPC®, is a Financial Advisor, Certified Financial Planner ™ practitioner with Ameriprise Financial Services, Inc. in Honolulu, HI with Na Ho’okele Financial Advisory Team, a financial advisory practice of Ameriprise Financial Services, Inc. He offers fee-based financial planning and asset management strategies and has been in practice for 29 years.
    Investment advisory products and services are made available through Ameriprise Financial Services, Inc., a registered investment adviser.
    Ameriprise Financial Services, Inc. Member FINRA and SIPC
    ©2016 Ameriprise Financial, Inc. All rights reserved. File #1397316

    You have the resources to turn your house into the dream home you’ve always wanted. Now, what? Here are some tips to help you plan your remodel. Compile your wish list. Prioritize your list by identifying what projects and features are important to you and your lifestyle. Use your list to determine the scope and…